
The industry is short of 100,000 advisors by 2034 and is answering with technology that saves hours. But here’s what the last decade says about where those hours end up.
In February 2025, McKinsey estimated that US wealth management will be short of roughly 100,000 advisors by 2034. About 110,000 advisors, holding 42% of industry assets, are expected to retire within the decade. Over the same period, the number of households working with a human advisor is projected to rise from 53 million to between 67 and 71 million.
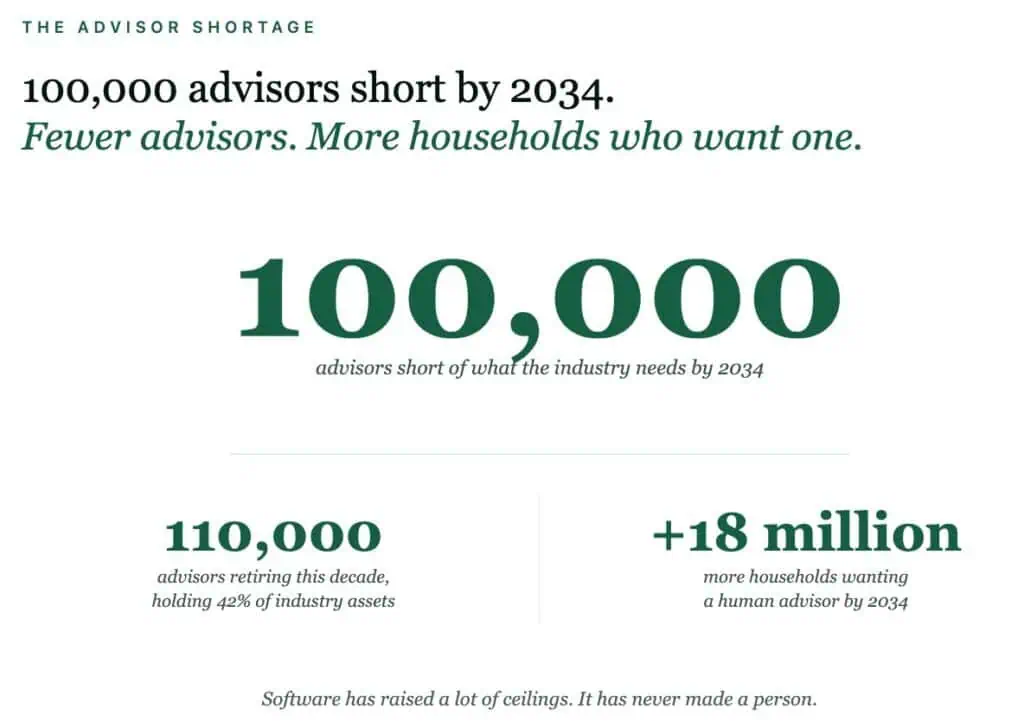
That estimate assumes advisor productivity stays where it is today. But AI is already absorbing large parts of the work that fills an advisor’s week outside of client meetings. Research, analysis, documentation and the administrative layer around every client interaction now take a fraction of the time they used to.
But making advisors faster will not close the shortage. The two things that actually limit growth in this business, client trust and the supply of trusted advisors, do not get faster. Advisors have gotten faster before, and the households without an advisor stayed without one.
Every time advisors got time back, the relationships they already had absorbed it
An advisor with a book of clients always has more they could be doing for those clients. There’s always another thing they could improve, another question they could answer, or another conversation they could have.
- • Between 2015 and 2024, revenue from fee-based advice in the US grew from about $150 billion to about $260 billion, while the advisor workforce grew 0.3% a year. The industry got much larger without getting much more populated, which means the gains landed inside relationships firms already had.
- • The market moved the same way. In late 2025, Schwab raised the bar for its advisor referral service from $500,000 to $2 million, effective 2026, and raised the fee alongside it. On 20 August 2026, the same minimum went from $2 million to $5 million.A referral program raises its floor when there is more demand for advisor time than there is advisor time.
- • Only about one in five advisory firms say they buy technology to save time or money. Roughly half say they buy it to raise the quality of what they deliver.
- • Kitces Research found that advisors who adopted it spent more time on planning, because better data let them go deeper with the client. The saved hours went back into the same relationship, and the client paid more for the deeper work.
An advisor’s limit is the number of relationships they can hold
Kitces Research says an advisor can realistically manage around 60–80 client relationships before the quality of service starts to decline.
The limit isn’t really about how many hours an advisor has in a week. It’s about how many people they can genuinely keep track of and maintain a strong relationship with.
That matters because the relationship is a big part of what clients are paying for.
Vanguard estimates that a financial advisor can add roughly three percentage points of value to a client’s returns. About half of that comes from behavioral coaching — mainly helping clients avoid making bad decisions, such as selling when markets are falling. Around 10% comes from implementing the portfolio efficiently.
In other words, much of an advisor’s value comes from talking with clients, understanding them, and helping them make better decisions. The more mechanical parts of the job are easier for software to handle.
Which is why more technology has not produced more clients per advisor.
Even as advisory software has improved, the number of clients each advisor manages has largely stayed the same. In some studies, it has even gone down. So recovered time flows toward depth, because depth is the only direction open to it. On the business side, that usually means taking on fewer, higher-value clients and moving upmarket.
AI might raise the limit. It cannot hold what the limit contains
The strongest argument for AI is that it changes the ceiling itself.
Earlier software made advisors faster without changing how many relationships one person could hold. AI could be different, because it absorbs much of the remembering and following-up that consumes an advisor’s capacity.
But the work AI is best at removing is the work that teaches new advisors how to become advisors.
Most of what a firm knows about its clients isn’t in the firm
Nobody becomes a trusted advisor by taking a course.
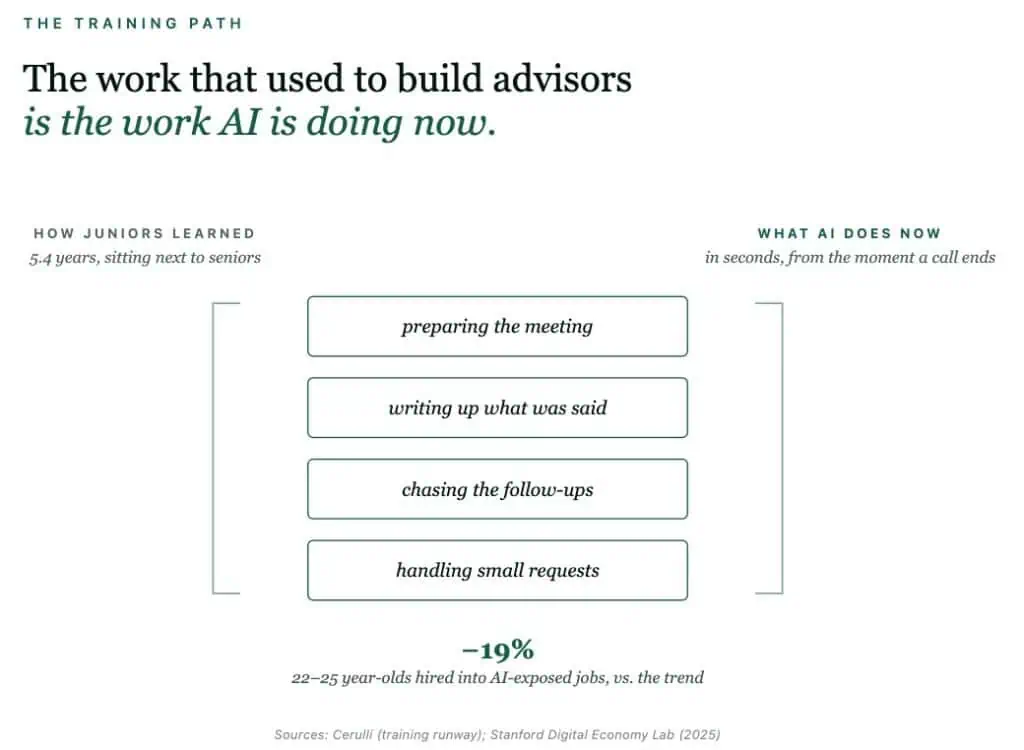
They get made by sitting next to someone senior for years — preparing the meeting, writing up what was said, chasing the follow-ups, handling the small requests that arrive between reviews. Cerulli puts the training runway at about 5.4 years, and roughly 7 in 10 new advisors leave before finishing it.
That list of tasks is also the list in every AI pitch made to a wealth management firm.
Stanford researchers tracking payroll data found that workers aged 22 to 25 in the occupations most exposed to AI are running about 19% below where their employment would otherwise be, and the gap comes almost entirely from firms hiring fewer of them. A junior with good AI looks capable quickly. Whether they are becoming experienced underneath is much harder to see, and the answer tends to arrive during the first conversation the AI cannot handle.
When 110,000 advisors retire holding 42% of industry assets, what leaves is not headcount. It is the only record of how those relationships work, and very little of it was ever written down. The industry already knows how easily that record moves: when an advisor changes firms, roughly 81% of client assets go with them.
The only other place the knowledge could live is the firm’s own systems, and most of those are CRMs. They record that a meeting happened on Tuesday and that a field was updated. They do not record how a difficult conversation was handled, or why a client was talked out of something they badly wanted to do. A system that files what happened is a very different thing from one that can show a new advisor how the job is done, and the second one is not what most firms are buying.
The firm has to hold what its advisors know
Two things are happening at once. Advisors are getting faster, and the industry is losing both the people who hold its client relationships and the apprenticeship that used to produce new ones.
Speed does not address either.
Both resolve in the same place. When the full history of a client relationship sits with the firm rather than in one person’s memory, a retirement becomes a handover instead of a loss, and a new advisor has something real to learn from before they have ever run a meeting alone. Whether judgment transfers this way in full is an open question, and firms will find out slowly, one retirement at a time. What is not in question is the alternative, which is losing the record entirely.
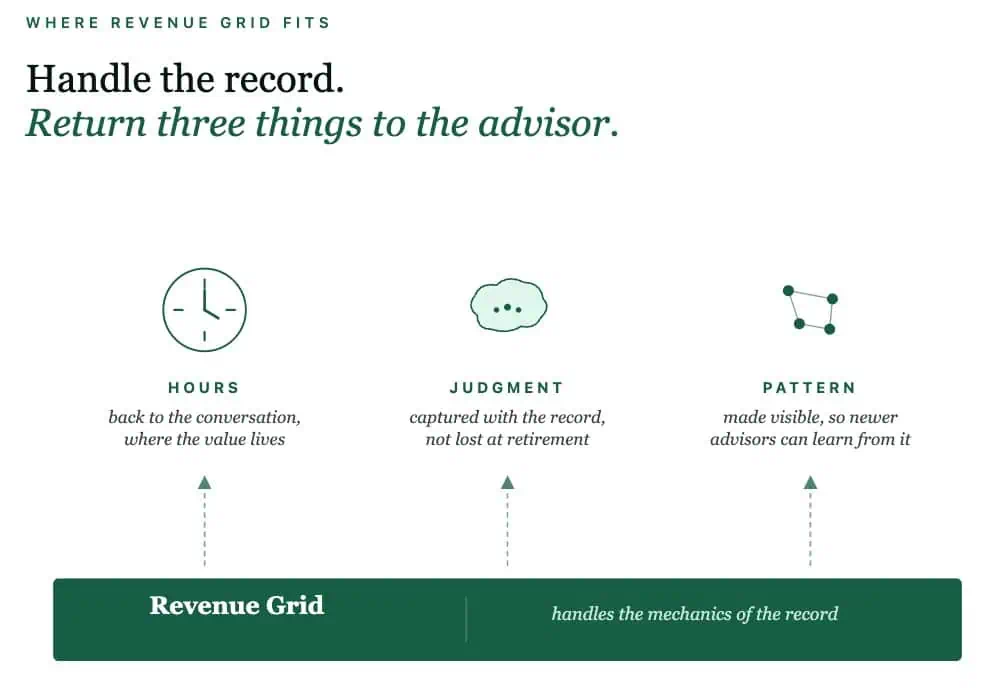
That is what relationship intelligence does, and it is what Revenue Grid was built for. Every email, meeting and calendar exchange is captured automatically and compliantly, then compiled into the context that explains a relationship rather than a log of what happened inside it. The record stays with the firm when the advisor doesn’t.
Speed will keep improving, and it will keep going into the same place. What changes the arithmetic is whether the relationship survives the person holding it. That question gets answered long before anyone retires, and most firms are answering it by default.